Coyfer specialism
Insurance for jewellers.
A risk that few brokers know how to place. We know which insurers accept it, what security measures they require and how to declare your stock so that the sum insured pays out.
All risks insurance tailored to your needs.
A great deal of value
in very little space.
A jewellery shop concentrates a great deal of value in a small space, and insurers rate it against very specific security requirements. We know those requirements and which insurers will accept the risk, something that is far from obvious if you knock on the wrong door.
The key to the insurance
Where is your stock?
Shop window, safe and travelling salesperson each have a different sum insured. Declaring each one correctly is what makes the policy pay out.
Pieces in display cases, on the counter and in the shop window while the shop is open. This is the sum most exposed to armed robbery and ram raids, and the one with the strictest security requirements.
- Security glass or anti-theft shutter
- Separate sum insured for display
Stock removed at closing time. The sum each insurer will accept depends on the certified security grade of the safe and on how the alarm is connected.
- Approved safe grade
- Alarm with monitoring centre
The sample collection carried by the owner or an employee on client visits and at trade fairs. It is insured under travelling salesperson cover, with its own terms and sums insured.
- Specific travelling salesperson cover
- National and international trade fairs
Sector-specific cover.
A programme designed for the jewellery trade, not an adapted retail policy.
- 01
Armed robbery and ram raids
Robbery with violence or intimidation, during or outside business hours, and damage from ram raids against the shopfront.
- 02
Display and safe
Stock in the shop window, display cases and safe, with a different sum insured for each location.
- 03
Travelling salesperson and trade fairs
Sample collection off the premises, on sales visits and at temporary exhibitions.
- 04
Deposit and consignment
Customers' pieces under repair and goods consigned to other retailers.
- 05
Buildings and glass
Premises, signage, shop windows, fixtures and security installations.
- 06
Public liability
Damage to customers and third parties on the premises.
Measures usually required.
Tick the ones you have. This helps us know which insurers will accept the risk and for what sums.
Tick the security measures at your premises.
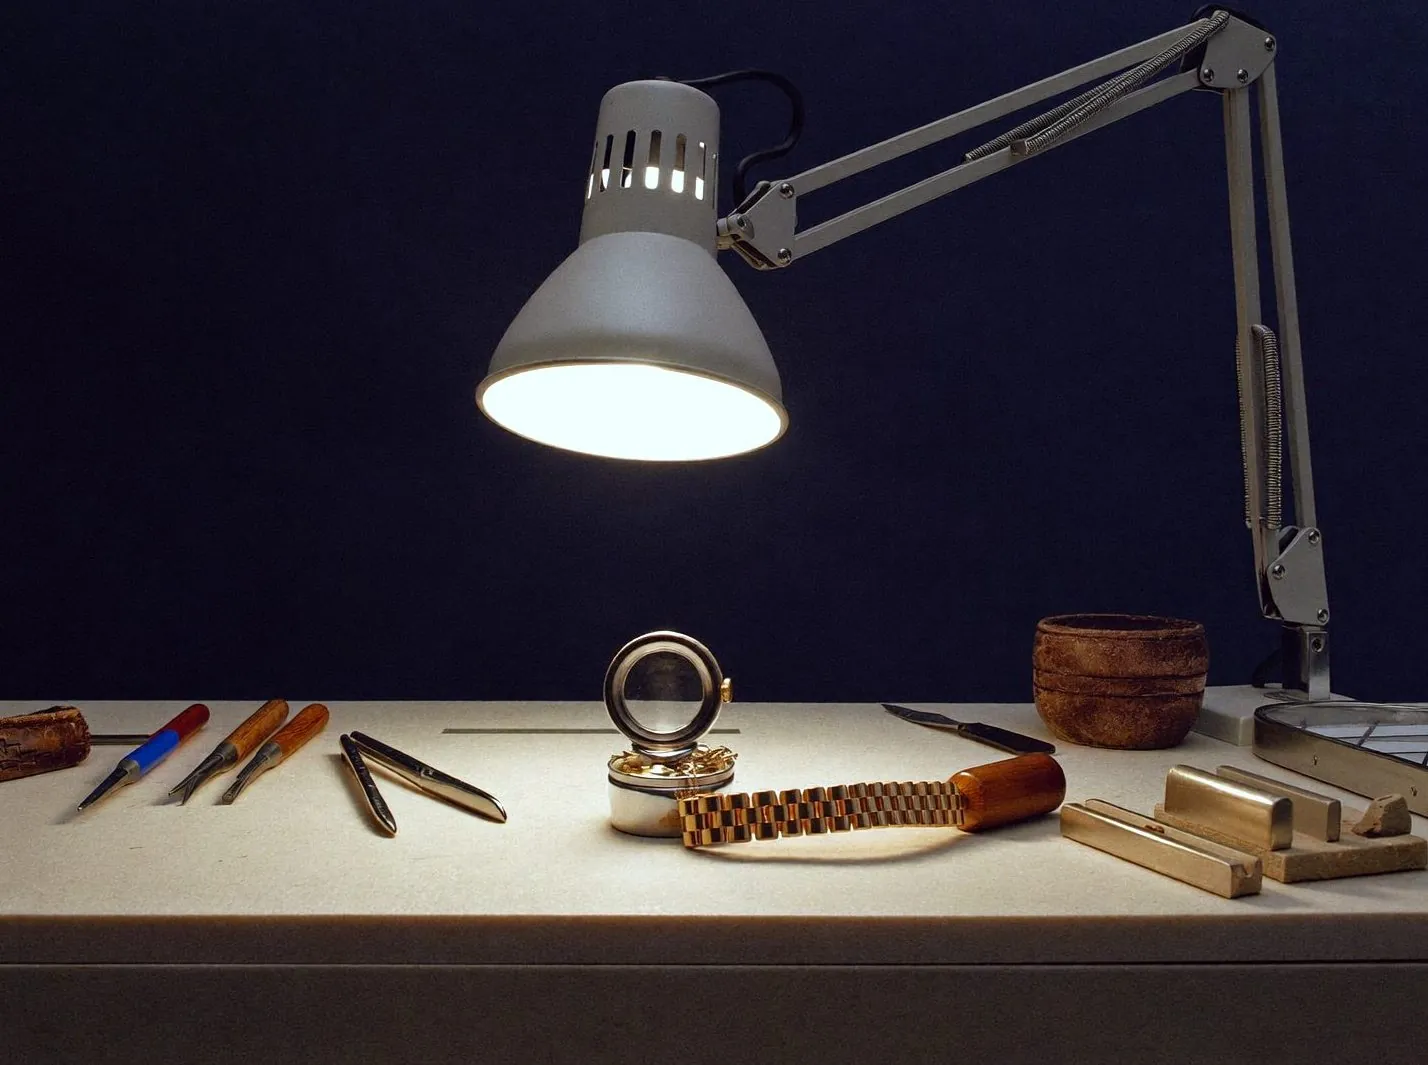
Workshop and deposit
Your customers' pieces count too.
Watches being serviced, jewellery under repair or goods consigned to other retailers. They are not yours, but if they are lost or damaged you are liable, and they often account for a significant share of the value in your custody.
What makes the difference. We review the actual distribution of your stock with you and declare your own goods and third-party goods separately.
Three situations in the sector.
- 01
An armed robbery during business hours takes pieces from the counter.
Robbery with violence or intimidation, up to the sum declared for display.
- 02
You travel to an international trade fair with part of the sample collection.
Travelling salesperson and temporary exhibition cover, on the agreed terms.
- 03
A customer's piece is damaged in the repair workshop.
Third-party goods held on deposit and liability for the premises.
Frequently asked questions.
What security measures do they require?
It depends on the sum insured: an approved safe, connection to an alarm monitoring centre and sometimes armoured glass. We confirm this before requesting a quote.
Is my stock covered when I take it to a trade fair?
Yes, with travelling salesperson and transit cover. It is a specific cover and must be taken out expressly.
What about third-party goods on deposit?
This is a standard cover in the sector and should be declared, as it often accounts for a significant share of the value.
A specialist risk deserves a broker who knows it.
Request a review